
For years, property platforms have promised to make the estate agent redundant. Search a database, estimate a home’s value, book a viewing, sign digitally, and close online: the process seems ripe for automation.
But the evidence suggests a less dramatic outcome. Platforms will probably absorb many tasks that agents do, but not agents.
The front end of the transaction is the strongest case for technology. Online portals have made finding property faster and more transparent. Automated valuations can use comparable sales, local data and market trends. Digital tools now handle everything from mortgage applications, identity checks, document management and virtual viewings (in some markets). Buyers and sellers can connect with each other without a gatekeeper.
The economics are changing too. In the United States, the National Association of Realtors’ 2024 Profile of Home Buyers and Sellers found that 88% of buyers and 90% of sellers used an agent. But the same report found a record low in the history of the survey with only 6% of sales being done directly by owners. Consumers do use the internet to research property but most still use professionals when money and risk are on the line.
That’s because a home is more than just a listing. It is a negotiation, a legal transaction and very often an emotional one. Algorithms can find similar properties; they can’t reliably judge a leaking roof, a hard chain, a seller’s urgency or a buyer’s willingness to compromise. They also struggle to resolve disputes when surveys find faults or a deal is coming apart.
This is further emphasized by the regulatory framework. The 2024 US settlement with the National Association of Realtors changed how compensation is displayed and required written buyer agreements in many cases. It didn’t eliminate agents or commissions. Instead, it made the value of representation more apparent—and perhaps more negotiable.
Platforms also face structural limits. Most do not own the underlying inventory, conduct viewings or carry the same professional responsibilities as brokers. Their valuations can be useful, but automated estimates are only as good as their data and are particularly vulnerable in unusual or thinly traded markets.
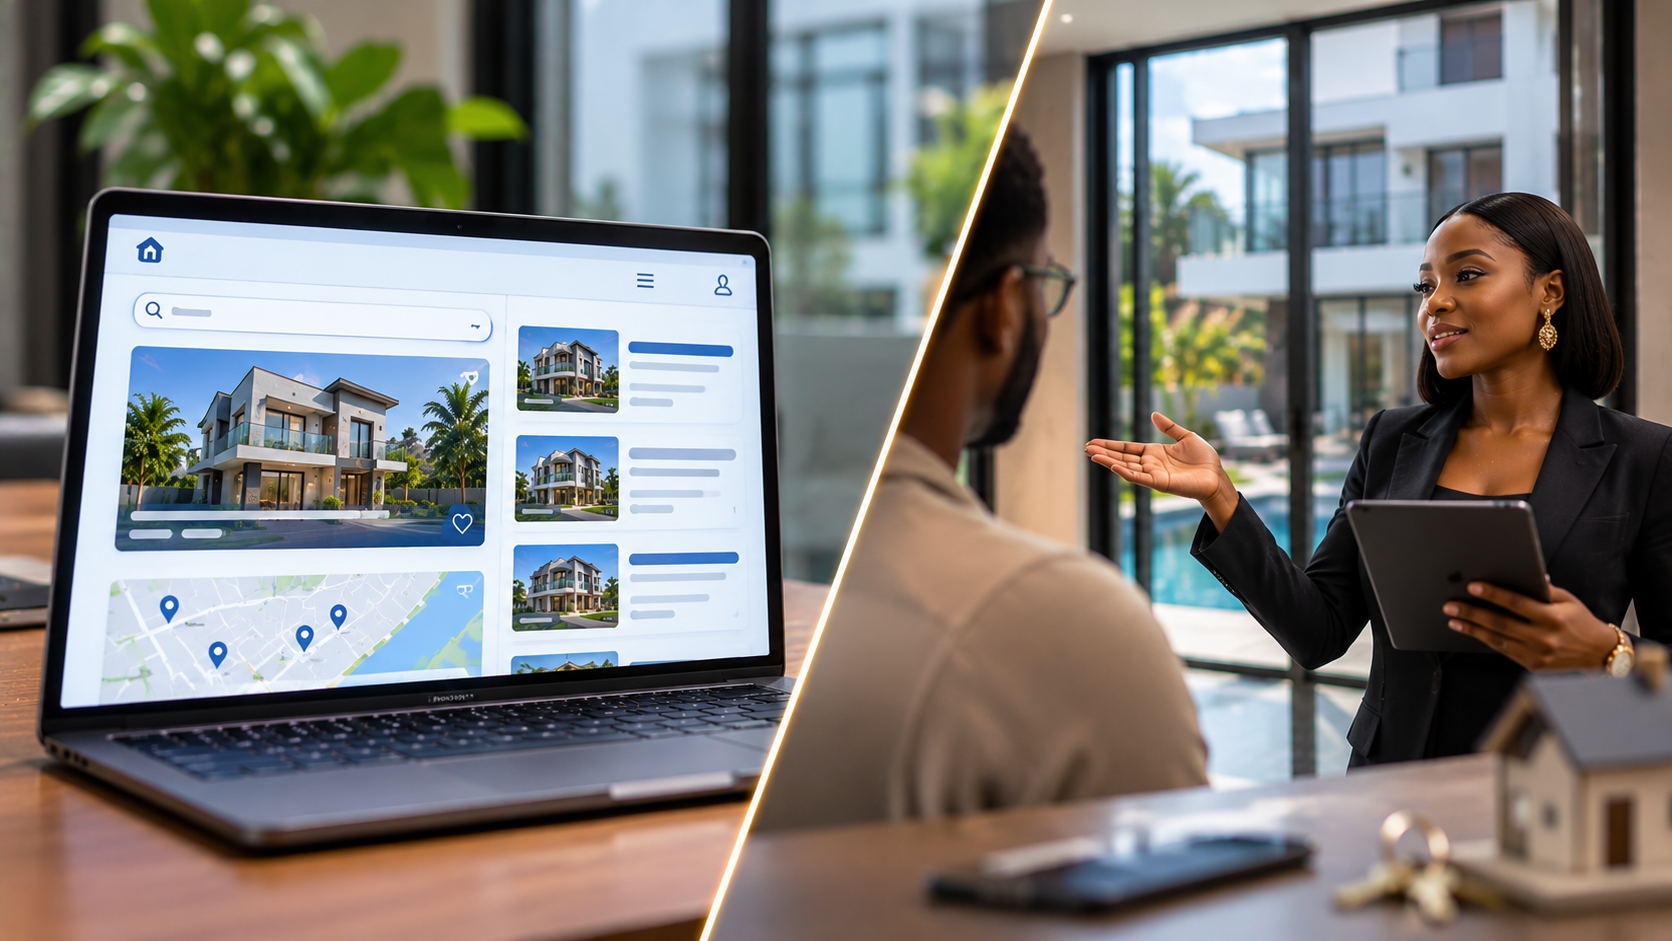
The likely future is therefore not “platform versus agent,” but platform plus agent. Routine work will be automated, and low-service or fixed-fee models will expand. Agents who merely open doors and upload photographs will struggle. Those who provide pricing judgment, negotiation skill, local expertise and transaction management will remain valuable.
Property platforms will not make agents disappear. They will make it harder for agents to justify being expensive, opaque or inefficient. In real estate, that may be the more consequential revolution.